Predicting Lifetime Value Without Fooling Yourself
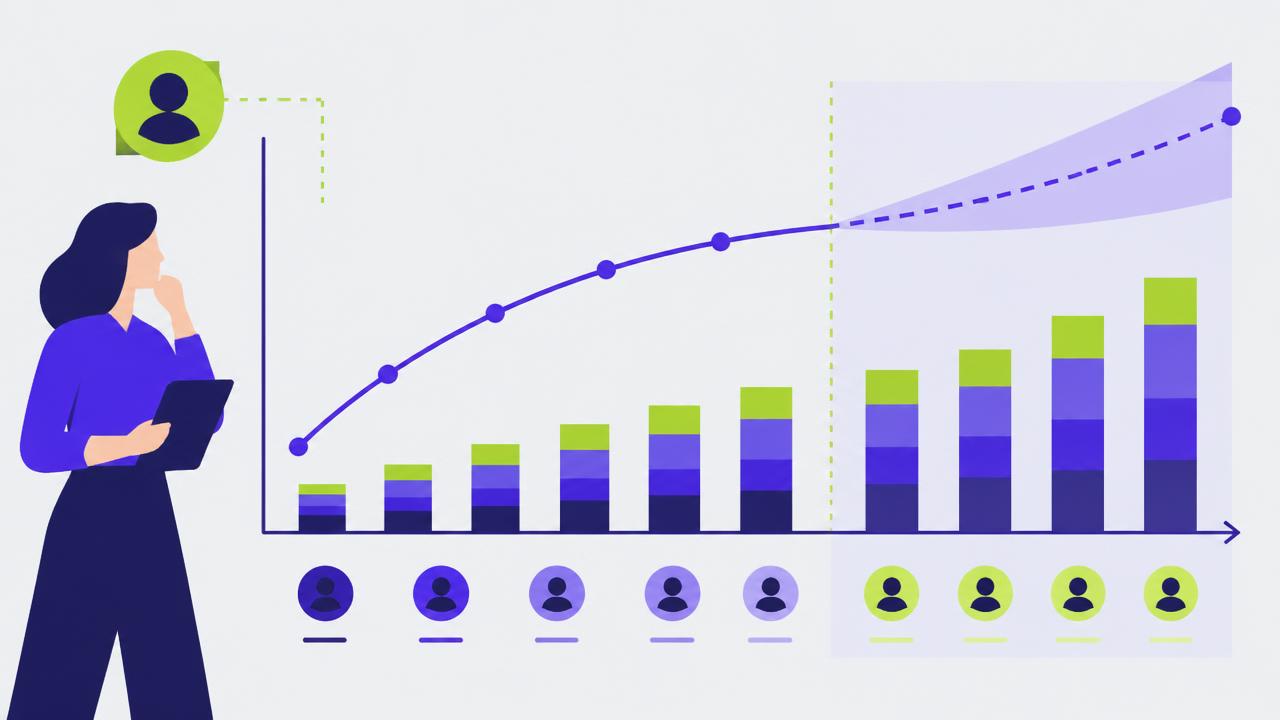
Lifetime value sits underneath every acquisition decision, which gives it a structural bias: a higher LTV justifies more spend, and there is always someone who wants to spend more. The defence is to build the model so that it can be proven wrong.
Pick a horizon you can check
Infinite-horizon LTV cannot be validated within the lifetime of a budget cycle. Predict 12-month or 24-month value instead. Those numbers can be back-tested against cohorts that have already reached that age, which means the model is accountable.
| Approach | Data needed | Best used when |
|---|---|---|
| Historical cohort average | 12+ months of cohorts | Stable business, simple product |
| Retention curve extrapolation | Cohort retention by month | Subscription models |
| Probabilistic purchase model | Transaction history per customer | Non-contractual commerce |
| Machine-learned regression | Rich behavioural features | Large scale, dedicated analyst |
Margin, not revenue
Revenue LTV compared against acquisition cost produces a ratio that looks comfortable and means nothing. Subtract cost of goods, payment fees, shipping, returns and the servicing cost of supporting that customer. What remains is what can actually fund acquisition.
The most expensive LTV mistakes come from forgetting returns and refunds in categories where both are routine.
Segment before you average
A single blended LTV hides the fact that customers from one channel are worth three times those from another. Compute curves by acquisition source and first-product-purchased at minimum; those two splits usually explain most of the variance and directly inform where to spend.
Watch for mix shift
An LTV model trained on customers acquired through one channel will overstate value when you scale a different one. Whenever the acquisition mix moves materially, refresh the curves before using them to justify further spend — this is the single most common way LTV-based budgets drift away from reality.
Related articles
The Quarterly Data Quality Audit
Most bad decisions made from data are not made from the wrong analysis. They are made from the right analysis on broken inputs.
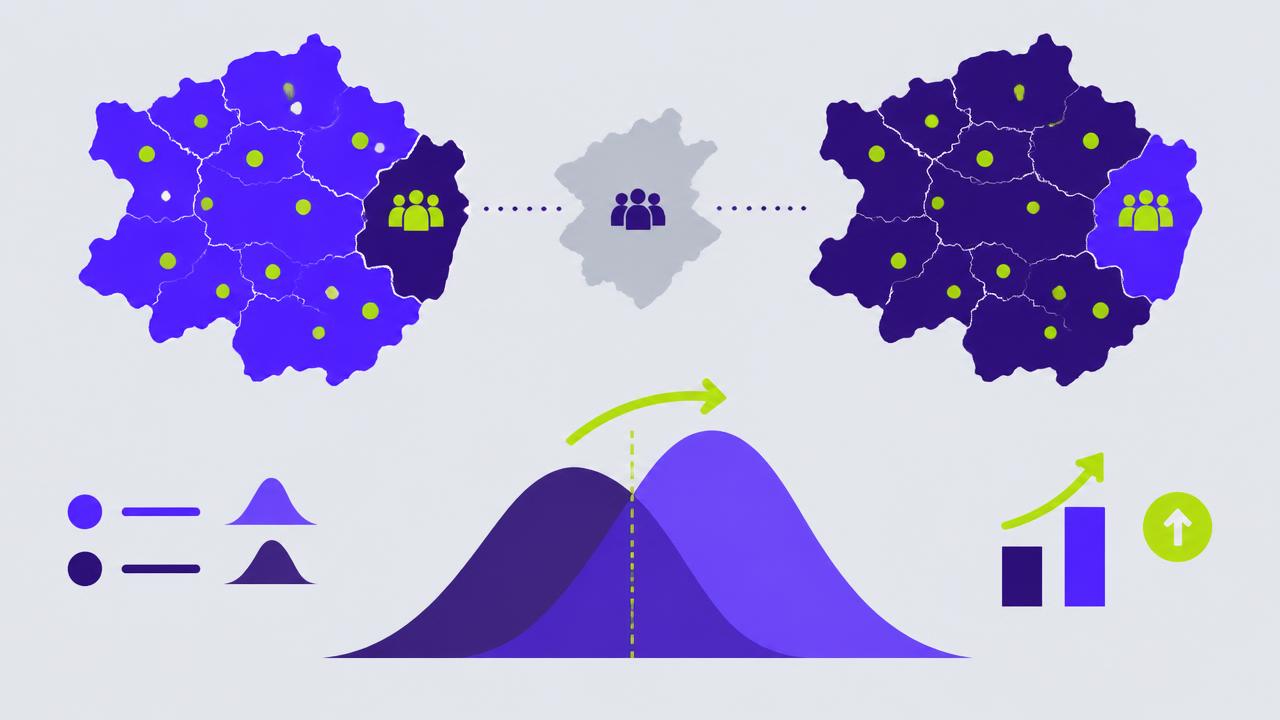
Incrementality Testing: The Only Number Your CFO Should Trust
Platform-reported ROAS answers "who touched the sale?" Incrementality answers "would it have happened anyway?" Only the second one supports a budget decision.
Geo Holdouts: The Most Practical Causal Test
When user-level tracking fails, geography is still a reliable way to build a control group.